
Mortgage Consulting
Mortgage Consulting and Advice Before You Apply
Unsure which loan suits you, how much house fits your budget or whether to refinance now? A free mortgage consultation with Sterling Smith gives you a plain-language plan, side-by-side program comparisons and honest next steps, with no obligation and no hard credit pull.
Advice Before the Application
Clarity first, paperwork later
Choosing a mortgage shapes your budget for years, sometimes decades. Yet many buyers pick a loan based on a headline rate or a friend's experience. A consultation flips that order: you learn how the options work for your income, savings and goals, and only then decide whether and when to apply.
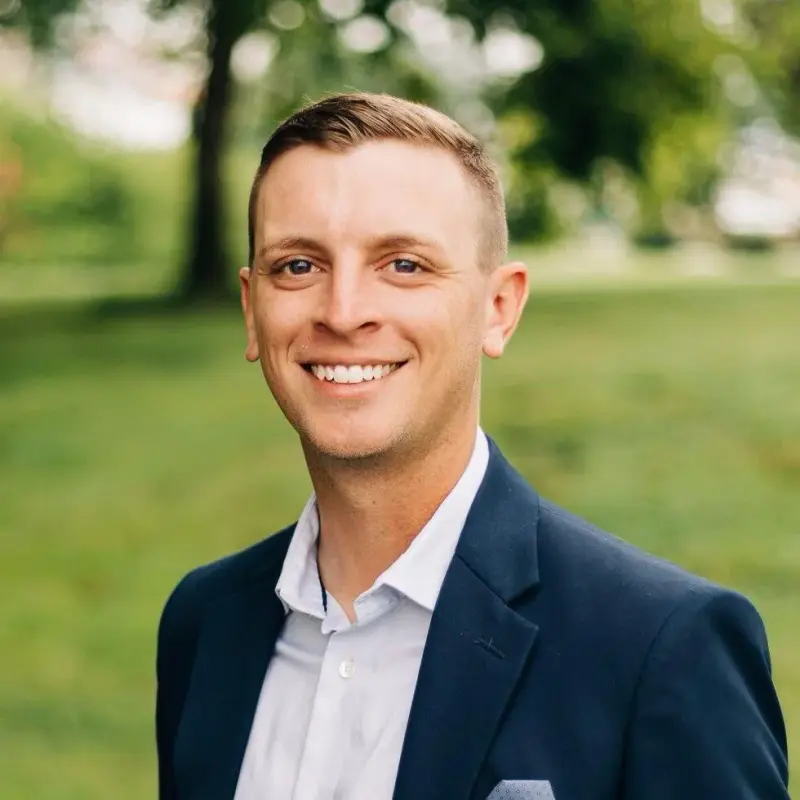
Sterling Smith, VP and Branch Manager of The Smith Mortgage Group, Powered by FCM, leads these conversations personally. Topics range from loan program selection and rate-lock timing to credit improvement, down payment planning and refinance break-even math. First-time buyers, move-up buyers, veterans, self-employed borrowers and investors all use the same free service.
There is no cost, no obligation and no hard credit inquiry to get started. You can talk by phone, by video or in person at our branch at 605 Delray Street in Shelbyville, Tennessee.
How We Help
Topics we cover in a consultation
Choosing a Loan Program
Compare conventional, FHA, VA, USDA, jumbo and Non-QM options against your goals, credit and down payment.
Rate and Refinance Timing
Understand rate locks, points and when a refinance recovers its costs so you act at a sensible moment.
Credit and Debt Readiness
Get practical steps to strengthen your score and debt-to-income ratio before you apply.
Affordability and Budgeting
Set a comfortable price range that accounts for taxes, insurance and closing costs, not just principal and interest.
Complex Income Strategy
Self-employed borrowers and investors learn which documentation paths fit, from bank statements to DSCR.
Who It Fits
A consultation is especially useful if you
- Feel unsure which loan program matches your situation and want an unbiased comparison
- Want a soft-pull pre-qualification before committing to a full application
- Are deciding whether to refinance now or wait for a better opportunity
- Need a plan to raise your credit score or reduce debt before buying
- Earn self-employment, commission or rental income that complicates qualifying
- Want to understand closing costs and how much cash to set aside
Prefer to explore first? Run scenarios with the affordability calculator or the loan comparison tool, then bring your questions to the call.
Know the Difference
Consultation, pre-qualification and pre-approval
These three steps are often confused. Here is what each one involves.
| Step | Credit check | Documents | What you get |
|---|---|---|---|
| Consultation | None | None required | Options, comparisons and a plan |
| Pre-qualification | Soft pull or none | Self-reported details | An estimated price range |
| Pre-approval | Full credit review | Income, asset and ID verification | A conditional approval letter for offers |
Ready to move beyond advice? You can start a pre-qualification online at any time. Once your documents are in, a pre-approval decision may take as little as 24 hours.
Common Scenarios
Questions a good advisor helps you answer
First-time buyers often want to know whether a low-down-payment FHA loan or a conventional loan with as little as 3%–5% down will cost less over time. The answer depends on credit, how long you plan to stay and how mortgage insurance is handled on each program, and we lay those trade-offs out in dollars rather than generalities.
Veterans and service members frequently ask how a VA loan compares with other options. Rural and small-town buyers may discover that a USDA loan is available for their address. Homeowners with an existing loan usually want to know whether a refinance, an extra payment strategy or simply staying put makes the most sense.
Investors and self-employed borrowers tend to need a longer conversation about documentation. We explain how bank-statement, DSCR and conventional qualification differ, then help you choose the path that balances cost with what you can realistically document. Every recommendation remains subject to qualification, underwriting and program guidelines.
How It Works
What happens after you reach out
Request a time
Call or text 931-205-9873, email sterling.smith@fcmhomeloans.com or use the contact form. We respond within two business hours.
Share your goals
We listen to your timeline, budget, income picture and any concerns, then ask the questions that shape your options.
Receive a clear plan
You get program recommendations, estimated costs and specific next steps, whether that means applying now or preparing over several months.
Proceed on your schedule
When you are ready, we guide you through pre-approval, underwriting and closing. If you are not ready, we stay available for follow-up questions.
Prefer to prepare before your call?
The first-time homebuyer guide and our mortgage FAQ explain common terms and steps, so you can make the most of your time with our team.
Browse GuidesAnswers
Mortgage consulting FAQs
Is there any charge for a mortgage consultation?
No. Consultations are free and carry no obligation. The aim is to help you make an informed decision, even if that decision is to wait.
What should I bring to my first conversation?
Nothing is required, but a rough idea of your income, monthly debts, savings and target price or current loan balance makes the conversation more specific. Recent statements help if you want detailed numbers.
Will talking to you affect my credit?
No hard inquiry is needed for a consultation or pre-qualification. A full credit review only happens if you decide to move forward with a pre-approval.
Can I meet virtually if I do not live near Shelbyville?
Yes. We are licensed to originate in all 50 states and handle most consultations by phone or video. In-person meetings at the Shelbyville branch are available by appointment.
How early should I talk to a lender before shopping for homes?
Ideally a few months ahead, especially if credit or savings need work. Even a few weeks before shopping gives you time to get pre-approved and understand your budget.
Do you only recommend loans you offer?
We explain the full range of programs we provide and tell you honestly when an option does not suit you, including when waiting or adjusting your plan makes more sense.
Keep Exploring
Related resources
Let's Talk
Questions about mortgage consulting?
Send a quick note and Sterling Smith will reply within two business hours (Mon–Fri, 9am–5pm CT). Prefer to talk now? Call or text 931-205-9873.
Loading the secure contact form… If it doesn't appear, call or text 931-205-9873 or email sterling.smith@fcmhomeloans.com.
Start Today
Ready to talk through your options?
Get a free, no-obligation consultation with Sterling Smith: clear answers, a side-by-side look at the programs you qualify for, and a plan built around your budget.